Gold in a World at War: Why the Safe Haven Stumbled
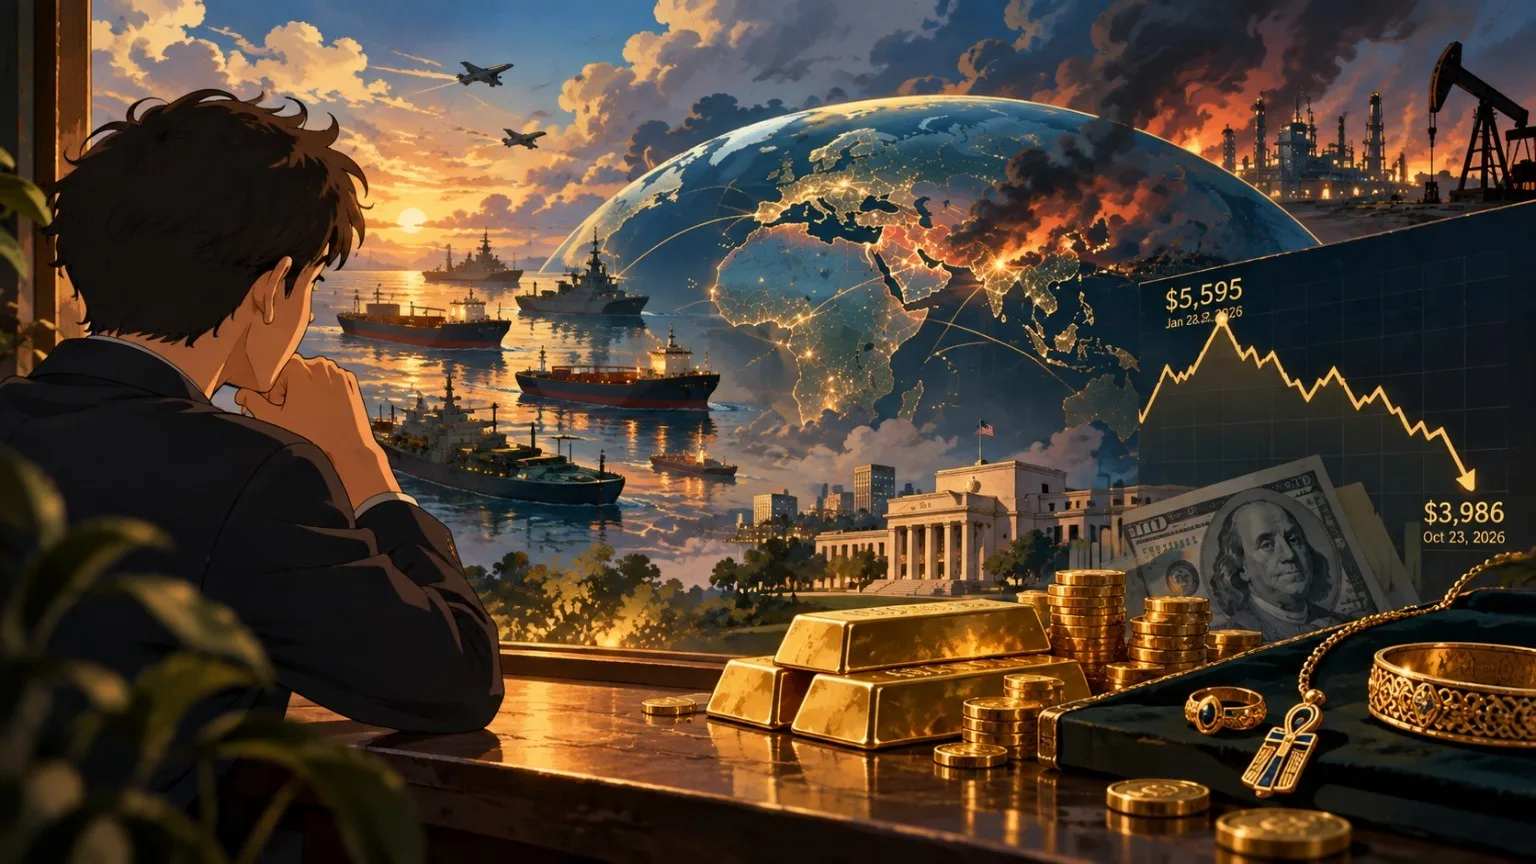
For most of history, a crisis sent people to gold. In 2026, the opposite happened at the worst moment. Conflict spread across the Middle East, oil climbed above $100, and gold fell below $4,000 an ounce for the first time since July. This article explains why, what the world's largest banks and institutions expect next, and what it means for anyone who buys or owns gold jewellery.
Where gold stands today
Price: about $4,000 per ounce on October 23, 2026, with a daily low near $3,986 (Kitco, Reuters).
Record: roughly $5,590 to $5,595 on January 28-29, 2026, depending on the data provider.
Distance from the peak: about 28% below the record, and about 4.6% down on the week, the sharpest weekly drop in over four months.
Year on year: roughly flat. A year of record central bank and ETF buying, plus a major war, left gold close to where it started.
Spot prices on selected dates, Oct 2026 (Kitco, Fortune; morning readings, approximate)
Gold last traded this low in mid-July.
The geopolitical picture
Three conflicts are shaping markets right now.
The US-Iran war. Strikes on Iran earlier this year were followed by attacks on tankers in the Persian Gulf and the Strait of Hormuz, and a US naval blockade is tightening around Iranian exports.
Houthi attacks on Saudi Arabia. Strikes on Saudi oil infrastructure, including the Shaybah field and the Red Sea port of Yanbu, led Washington to order non-emergency staff to leave the kingdom. Saudi Aramco says production has not been affected.
Russia and Ukraine. Ukrainian strikes on Russian refineries have kept diesel prices high.
The result: Brent crude reached its highest level since spring, trading above $100 a barrel (outlets reported figures between roughly $102 and $117 during the week). Reports also say US and Israeli planners have drawn up options for renewed strikes on Iran after the November 3 US midterm elections. No approval has been reported.
Five forces behind gold in 2026
Gold rarely moves on conflict alone. These five forces explain why war has not lifted it this autumn.
1. Geopolitical tension and safe-haven demand. Conflict, sanctions, and disrupted trade usually push investors toward stores of value, and that demand is real: gold ETF holdings ended September at a record 4,256 tonnes. But the same shocks can force investors to sell assets, gold included, to raise cash. When tech stocks fell this week, bonds rather than gold received the flight to safety on October 22.
2. Oil prices and inflation. Attacks on Gulf shipping and Saudi infrastructure have lifted Brent crude above $100 a barrel. The chain runs from disruption to higher energy costs, inflation fears, higher expected interest rates, and pressure on gold. The same war that creates safe-haven demand also creates conditions that weigh on gold.
3. The Federal Reserve and interest rates. Gold pays no interest. The Fed raised rates in September for the first time since 2023, and the 10-year Treasury yield has moved above 5%. Fed decisions and inflation data can matter as much as geopolitical headlines.
4. Central banks and reserve diversification. Central banks bought about 289 tonnes in the second quarter of 2026, up 62% from a year earlier, after a first quarter later revised down to about 57 tonnes (World Gold Council). The council expects another strong year, though below 2025. Total demand was flat at 1,269 tonnes in Q2, and jewellery demand has weakened at these prices. This support softens falls but does not stop them.
5. The US dollar and investment flows. Gold is priced in dollars, so a firm dollar makes it costlier for buyers elsewhere. Flows also amplify moves: ETF holdings reached a record in September while futures traders were liquidating positions, a gap the World Gold Council called unusual.
Together, these forces explain why gold can fall on a day when the geopolitical news gets worse.
What the largest banks expect
Forecasts have been lowered this year, but nearly all still point higher for 2027.
Institution
End of 2026
2027
Goldman Sachs
$4,650 (cut from $4,900 on Sept 18)
$5,400 by end-2027
UBS
$4,600 (December)
$5,000 (March), $5,200 (June), $5,400 (September)
J.P. Morgan
$4,500 (Q4)
$5,400 by Q4 2027 (last restated before its mid-year cut)
Citi
$4,500 (Q4)
Not restated recently
Bank of America
About $4,000 (Q4 average), possible low of $3,750
$4,813 full-year average
HSBC
Not reported
About $5,025 by end-2027
These targets come from different dates and horizons, so they are not a consensus or a promise. Some outlets still show older figures, such as Goldman at $4,900 or J.P. Morgan at $6,000 for the fourth quarter, so check the date of any forecast you read. The World Gold Council's July baseline was a second-half trading range around $4,100, as reported. Bank of America's most bullish scenario reaches $8,000, well outside the consensus. CPM Group, an independent research firm, named $3,800 and $3,500 as support levels.
What to watch next
October 27-28: the Federal Reserve meeting. Markets price a hold as most likely, with a small chance of another hike.
November 3: US midterm elections, which several analysts link to both gold and the pace of Iran policy.
Oil and Hormuz: a de-escalation could lower oil and ease rate fears, which would help gold. A deeper supply shock could do the opposite in the short term.
Central bank buying: the clearest long-term support.
Three possible paths for gold
These are scenarios, not predictions.
A renewed rise: Escalating risks, weaker growth, falling yields, or fresh investment demand could lift gold. The banks' 2027 targets of $5,000 to $5,400 assume something like this.
A period of consolidation: If uncertainty persists but rates and the dollar stay firm, gold could trade in a broad range, as the World Gold Council's baseline suggests.
Further downside: Hotter inflation, rising real yields, a stronger dollar, and continued investor selling could push gold lower even if conflict continues. Bank of America's possible low of $3,750 and CPM Group's support levels show where analysts see that risk.
What this means for jewellery customers in Egypt
The international price is only one part of what you pay in Egypt. The final price also reflects the USD/EGP exchange rate, local market conditions, applicable costs and taxes, and the piece's karat, weight, and making charges.
A fall in the international price therefore does not always mean the same fall in the Egyptian price, because currency moves and local conditions can change the result. Understanding the difference between the international benchmark and the final retail price is more useful than reacting to a single headline.
The Kenooz perspective: understand the forces, not just the price
Gold's price comes from geopolitics, monetary policy, currencies, central bank demand, and investor behaviour. The most useful question is not whether gold will rise or fall. It is which forces dominate the market right now, how reliable the evidence is, and what could change the outlook.
At Kenooz, we believe informed customers deserve clear explanations rather than dramatic predictions. We will always show you the gold price and making charges openly, so you can decide with context and confidence.
Research note: market prices and forecasts are time-sensitive. Figures reflect publications available as of October 24, 2026. This article is for general information and is not investment advice.
Sources
Kitco; Reuters; Bloomberg; CNBC; The National; Oilprice.com; APMEX; World Gold Council (Gold Demand Trends Q1 and Q2 2026); ING; Goldman Sachs, UBS, J.P. Morgan, Citi, Bank of America, and HSBC forecasts as reported by financial media through October 23, 2026.
Kenooz Journal | October 24, 2026